

Abstract:
This study critically examines the dual implications of artificial intelligence (AI) in accounting, highlighting its potential benefits. The study argues that the increasing integration of AI into accounting and financial practices necessitates a comprehensive reassessment and modernization of existing ethical and professional frameworks. Drawing on contemporary ethical standards and professional guidance issued by leading international bodies, the study emphasizes the indispensable role of human judgment, professional skepticism, and ethical accountability in AI-assisted decision-making. Ultimately, it contends that technological advancement must be accompanied by robust ethical oversight to preserve professional integrity, ensure accountability, and maintain public trust in the accounting profession (Ballantine, 2024; IESBA, 2024).
Keywords: artificial intelligence, accounting ethics, transparency, professional responsibility, ESG, IESBA, ACCA, AICPA
1. Introduction
Artificial intelligence has irrevocably altered the landscape of the accounting profession, fundamentally transforming core functions such as financial reporting, auditing, and enterprise risk management. The deployment of advanced analytics and machine learning allows systems to achieve a level of efficiency and predictive accuracy that vastly outperforms isolated human judgment (Marr, 2018; Omoteso, 2012). Yet, this rapid technological adoption forces the industry to confront complex ethical and operational paradoxes. While AI delivers data-driven perspectives and real-time anomaly detection, it simultaneously obscures the decision-making process, raising critical questions regarding accountability, transparency, and professional boundaries (Tan & Low, 2019). This study provides a subjective, detailed critique of AI applications in accounting, evaluating both the substantial benefits and the inherent dangers to professional integrity, asserting that technological advancement must never eclipse human oversight (Ballantine, 2024).
2. Research methodology
This study adopts a critical conceptual and doctrinal review methodology to evaluate the systemic impacts, governance challenges, and ethical paradigms surrounding AI integration in accounting and ESG reporting. Rather than relying on empirical econometric modeling, this research employs a normative, multi-dimensional analytical approach to synthesize theoretical discourse, regulatory frameworks, and emerging industry practices.
2.1. Source identification and data collection
The research draws upon a purposive literature and document retrieval strategy across three principal domains:
- Global Institutional Standards and Regulatory Directives: Core policy frameworks, exposure drafts, and ethics guidelines issued by authoritative bodies, including the International Ethics Standards Board for Accountants (IESBA), the Association of Chartered Certified Accountants (ACCA), the American Institute of Certified Public Accountants (AICPA), and CPA Australia (2020-2024).
- Academic and Peer-Reviewed Literature: Interdisciplinary studies on accounting information systems, algorithmic bias, professional skepticism, and AI ethics sourced from Scopus, Web of Science, and Google Scholar (e.g., Critical Perspectives on Accounting, Accounting Horizons, AI & Society).
- Industry Benchmarks and Case Deployments: Technical whitepapers and documented enterprise implementations of predictive analytics and generative AI platforms (e.g., PwC’s GL.ai, KPMG’s deployment of MindBridge, Deloitte’s Omnia GenAI).
2.2. Analytical framework
To systematically examine the duality of AI, the analysis is structured around a dialectical critique that bridges operational breakthroughs with critical systemic risks. Specifically, it contrasts tangible audit efficiencies against algorithmic vulnerabilities such as opacity and bias, while simultaneously interrogating the ESG dual-audit dimension: weighing AI’s efficacy in countering greenwashing against the substantial environmental costs of hyperscale computational infrastructure.
2.3. Interpretive synthesis
The retrieved normative policies and empirical findings were synthesized through a comparative institutional lens. This process assesses how existing ethical codes (e.g., IESBA Code of Ethics) withstand algorithmic disruption and identifies structural interventions required across accounting curricula, firm-level governance, and regulatory oversight.
Building upon this methodological and interpretive framework, the subsequent section delineates the core algorithmic architectures currently deployed across the accounting ecosystem, laying the foundational context for the dialectical critique of operational efficacy versus systemic vulnerabilities that follows.
3. Research content
3.1. Artificial intelligence and its applications in accounting
Artificial intelligence spans a wide range of computational technologies designed to replicate, enhance, or extend human cognitive abilities such as learning, reasoning, and problem-solving. Techniques like machine learning, natural language processing, robotics, and predictive analytics enable systems to detect patterns, process unstructured data, and deliver real-time insights at a scale far beyond human capacity (Marr, 2018; Mökander, 2023). In the modern accounting ecosystem, these capabilities are no longer theoretical; they have become deeply ingrained into everyday practice. Automated bookkeeping tools drastically reduce manual data entry and improve baseline accuracy, while AI-driven audit platforms sift through vast transaction datasets to spot anomalies and potential fraud with surgical precision. Furthermore, predictive models support sophisticated financial forecasting and risk assessment, and natural language processing powers everything from automated narrative report generation to interactive client communication via intelligent chatbots (Omoteso, 2012; Richins et al., 2017).
The profession has largely embraced these developments with optimism, citing tremendous gains in operational efficiency, radical cost savings, and the overall enhancement of decision-making quality. For instance, advanced anomaly detection and predictive analytics not only strengthen audit quality but also provide corporate management with crucial early warnings of emerging financial vulnerabilities (Dell, 2024; Schweitzer, 2024). Likewise, natural language tools can render interactions with clients and regulatory bodies faster, clearer, and far more transparent (Ballantine, 2024; Tan & Low, 2019). Nevertheless, as AI comprehensively reshapes the operational landscape, it aggressively forces difficult, unavoidable conversations about professional ethics. When algorithms begin to significantly influence reporting and dictate audit outcomes, foundational questions of accountability, transparency, and systemic bias inevitably surface. For this very reason, the integration of AI into accounting must be strictly guided by robust ethical frameworks that safeguard the public interest and rigorously uphold the profession’s long-standing commitment to absolute integrity (Omoteso, 2012).
3.2. The efficacy of AI: Analyzing the advantages
The application of AI in accounting provides measurable, data-driven improvements across multiple functional domains, primarily driven by the extraordinary ability of machine learning to process unstructured data at an unprecedented scale (Marr, 2018; Mökander, 2023).
A primary and perhaps the most impactful advantage of AI is its capacity to revolutionize fraud detection by replacing traditional, risk-prone audit sampling with real-time, comprehensive data analysis (Omoteso, 2012). In the past, auditors were forced to rely on limited sample sizes, inherently leaving room for undetected errors or malicious activities. Today, anomaly detection systems developed through industry partnerships, such as the collaboration between KPMG and MindBridge Analytics, can seamlessly and continuously evaluate entire populations of financial transactions (KPMG, 2024). These advanced systems accurately identify highly nuanced, suspicious patterns-ranging from duplicate invoicing schemes to irregular, hidden vendor associations-that routinely fall below standard human approval thresholds.
Furthermore, AI significantly elevates the discipline of financial forecasting through advanced predictive analytics. Sophisticated machine learning models, including enterprise solutions like Deloitte’s GenAI, project future cash flows and simulate complex, multi-variable credit risk scenarios with a level of precision that thoroughly eclipses manual, spreadsheet-based methodologies (Deloitte, 2025; Tan & Low, 2019). By aggressively analyzing real-time, unstructured data streams from global financial markets, supply chain logistics, and shifting client behaviors, accountants are equipped with a dynamic, forward-looking view of emerging financial risks. This shifts the accountant's role from a historical record-keeper to a strategic, proactive financial advisor.
Finally, the sheer operational efficiency achieved through audit automation cannot be overstated. Technological platforms such as PwC’s GL.ai streamline the processing of complex expense reports, dense legal contracts, and voluminous financial statements at an industrial scale (PwC, 2020; Richins et al., 2017). This relentless automation drastically reduces the immense amount of time typically allocated to routine, manual verification tasks. Consequently, auditors are liberated from administrative burdens, allowing them to redirect their intellectual focus toward higher-level interpretive analysis, strategic risk assessment, and complex ethical judgments where human cognition remains superior (Marr, 2018).
3.3. Systemic vulnerabilities: Analyzing the disadvantages
Despite the overwhelming and heavily documented efficiency gains, the unquestioned, rapid reliance on AI introduces critical systemic vulnerabilities that severely threaten the foundational trust of the accounting profession.
The most profound disadvantage of AI integration is the pervasive "black box" dilemma, which results in a dangerous loss of transparency (Tan & Low, 2019). Modern machine learning algorithms, particularly deep neural networks, operate in ways that are inherently opaque. When these complex models generate high-stakes financial conclusions that even their own technical developers cannot fully trace, deconstruct, or logically explain, the core concept of accountability is severely compromised. This opacity makes it exceedingly difficult, if not impossible, for stakeholders, regulatory bodies, and the auditors themselves to independently verify the underlying logic and absolute reliability of AI-generated financial outputs (Dell, 2024).
Compounding the issue of transparency is the persistent threat of algorithmic bias and the degradation of data integrity. Because AI systems must be trained on vast troves of historical financial data, they are highly susceptible to inheriting, learning, and ultimately amplifying existing human biases or long-standing systemic inequalities (Mökander, 2023). If the foundational input data is fundamentally flawed, unrepresentative, or historically prejudiced, the AI will operate under a false paradigm. Consequently, it will quickly generate misleading and objectively unfair financial assessments, such as discriminatory credit risk profiling, directly undermining the accounting profession's strict mandate for neutrality and objectivity (Schweitzer, 2024).
Equally critical are the escalating cybersecurity and confidentiality threats inherent to digital transformation. The bedrock of professional accounting ethics relies heavily on the absolute protection of client confidentiality. The aggressive, industry-wide migration of highly sensitive, proprietary financial datasets to cloud-based AI platforms exponentially increases the digital surface area exposed to malicious actors. This centralization of valuable data creates lucrative targets, drastically elevating the risk of unauthorized access, catastrophic data breaches, and sophisticated cyber-attacks (Mökander, 2023; Richins et al., 2017).
Perhaps the most insidious vulnerability is the psychological erosion of human judgment. As automation becomes more sophisticated, there is a growing, dangerous tendency for practitioners to fall victim to over-reliance on automated outputs without sufficient critical review (Omoteso, 2012). When AI is culturally treated within a firm as an infallible oracle, the critical role of human professional skepticism is severely diminished. This creates dangerous "grey areas" in legal and moral responsibility, leaving firms highly exposed when algorithmic errors, subtle hallucinations, or undetected financial misconduct inevitably occur (Ballantine, 2024).
3.4. The ESG paradox: AI in sustainability reporting
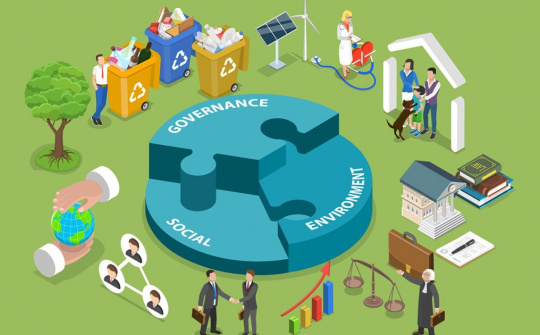
As the global accounting paradigm shifts aggressively toward environmental, social, and governance (ESG) metrics, AI is increasingly positioned as the ultimate tool for sustainability reporting. However, critically evaluating this intersection reveals a complex, double-edged sword that tests professional ethics.
Sustainability reporting fundamentally differs from traditional financial accounting; it relies heavily on massive, fragmented, and unstructured datasets—ranging from global supply chain carbon emissions and IoT sensor data to social sentiment analytics. AI and advanced machine learning models provide an undeniable operational advantage by aggregating and synthesizing this disparate data at unprecedented speeds. Furthermore, the Association of Chartered Certified Accountants (ACCA) explicitly notes that AI possesses the analytical capability to cross-reference corporate sustainability claims against independent, real-time datasets, thereby serving as a powerful technological countermeasure against corporate "greenwashing"—the deceptive practice of exaggerating environmental efforts (ACCA, 2021).
Conversely, the deployment of AI in ESG introduces severe systemic risks and profound ethical paradoxes. The most glaring contradiction is the immense carbon footprint generated by AI itself. Training and sustaining large language models (LLMs) and predictive algorithms require hyperscale data centers that consume staggering amounts of electricity and cooling water (ACCA, 2023). Thus, utilizing highly energy-intensive AI systems to measure and report on a company's sustainability creates a direct, undeniable conflict with the very environmental goals the reporting seeks to achieve.
Furthermore, unlike deeply entrenched financial reporting standards, global ESG data frameworks remain highly fragmented and largely unstandardized. If machine learning models are trained on inconsistent, low-quality, or manipulatively curated ESG data, the algorithms will suffer from severe data voids. In this scenario, AI transforms from a tool of transparency into an instrument of "automated greenwashing," generating highly convincing but fundamentally flawed sustainability reports that can easily deceive stakeholders and regulators (Mökander, 2023). Therefore, true professional responsibility demands a rigorous dual-audit: accountants must not only utilize AI to verify corporate sustainability metrics, but they must also strictly account for, measure, and transparently report the specific carbon emissions generated by their firm's own algorithmic infrastructure (ACCA, 2021).
3.5. Institutional standards and reconceptualizing ethical frameworks
To successfully survive this unprecedented technological disruption, global accounting standard-setters are urgently reinterpreting their foundational ethical frameworks for the digital era. The International Ethics Standards Board for Accountants (IESBA) has explicitly recognized the severe risks posed by technology, amending its Code to strictly prohibit delegating professional responsibility to a machine. Notably, the IESBA now officially recognizes "automation bias" - the dangerous psychological tendency to favor technology-generated outputs even when contradictory information is present—as a direct threat to objectivity and professional judgment (IESBA, 2024). Furthermore, the IESBA mandates that relying on opaque or unexplained AI outputs is ethically unacceptable; accountants must independently evaluate data quality, limitations, and the exact extent of their reliance on machine conclusions (IESBA, 2024).
Similarly, the ACCA argues that while AI will turbo-charge the global economy, the profession must act as the primary governance bridge between innovation and public trust. The ACCA emphasizes that accountants must dictate the "tone at the top," championing outcomes-based regulation and aggressively challenging the unethical use of AI in ESG reporting (ACCA, 2021; ACCA, 2023). By prioritizing ethical data management, the ACCA views the accountant not merely as a user of technology, but as its chief ethical guardian.
In the United States, the American Institute of Certified Public Accountants (AICPA) rigorously applies its Code of Professional Conduct to AI utilization. The AICPA warns that the allure of AI must never compromise auditor independence or client confidentiality. According to AICPA standards, practitioners must apply an elevated degree of professional skepticism when evaluating AI-generated financial data, demanding rigorous source citations and ensuring strict data retention and security policies are upheld when interfacing with third-party generative models (AICPA & CIMA, n.d.).
Finally, CPA Australia reinforces these global mandates by focusing on foundational competence, asserting that mastery of traditional accounting standards is no longer sufficient. CPA Australia actively mandates that finance professionals must undergo targeted training in algorithmic bias, fairness, and ethical AI implementation, proving that digital fluency is now an absolute prerequisite for maintaining professional competence (CPA Australia, 2024). Across all these global institutions, the consensus is absolute: technology does not break the ethical framework, but it ruthlessly challenges it, demanding that human skepticism remains the final arbiter of financial truth.
3.6. Recommendations for the profession
Addressing the severe friction between AI's extreme operational efficiency and its inherent ethical risks requires coordinated, structural action across multiple levels of the profession.
First and foremost, comprehensive educational reform is urgently required. Academic institutions and university accounting programs must fundamentally overhaul their curricula. AI ethics, algorithmic logic, data governance, and cybersecurity principles must immediately become mandatory, core competencies rather than elective afterthoughts. Educators should heavily utilize complex, case-based scenarios to prepare future professionals for the ambiguous, highly automated environments they will inevitably face, ensuring they graduate with both technical prowess and ethical resilience (Ballantine, 2024; Tan & Low, 2019).
On the regulatory front, there is a desperate need for continuous modernization. Global professional organizations and standard-setting boards must continue to issue aggressive, highly practical guidelines that directly address machine bias, algorithmic transparency, and the exact boundaries of legal accountability in AI-driven audits (Dell, 2024). Vague, high-level principles are no longer adequate; practitioners need concrete frameworks to navigate the liability of machine-generated errors.
Finally, strong corporate governance within individual accounting firms is the last line of defense. Firms must mandate and enforce a strict operational balance between human oversight and machine capability (Omoteso, 2012). Internal policies must dictate that ultimate sign-off responsibility must always rest with human judgment, explicitly forbidding full autonomy for high-stakes financial decisions. Additionally, continuous, rigorous professional development in advanced cybersecurity protocols is absolutely non-negotiable to protect highly sensitive client data from the escalating threat of cyber warfare (Schweitzer, 2024).
4. Conclusion
The widespread, aggressive adoption of artificial intelligence in accounting is a defining ethical crucible for the modern era. While the technology yields undeniably massive, disruptive advantages in sheer processing speed, comprehensive fraud detection, and dynamic predictive accuracy (Marr, 2018; Omoteso, 2012), its inherent disadvantages cannot be marginalized. The critical vulnerabilities-namely the "black box" lack of transparency, the insidious nature of systemic data bias, the environmental paradox of its massive energy consumption, and the escalating threats to data security-pose existential risks to the profession's credibility (Mökander, 2023; Richins et al., 2017). AI is undeniably a highly effective, powerful programmed tool, but it fundamentally lacks moral intuition, contextual awareness, and the capacity for ethical reasoning. Therefore, technological innovation must be heavily and continuously governed by uncompromising human professional skepticism. By aggressively modernizing regulatory frameworks in alignment with IESBA, ACCA, and AICPA standards, overhauling educational criteria, and embedding strict ethical data practices into the core operations of every firm, accountants can ensure that AI serves to amplify, rather than permanently erode, the vital pillars of integrity, objectivity, and public trust (Dell, 2024).
References:
ACCA. (2021). Ethics for AI adoption: connecting AI and ESG. Association of Chartered Certified Accountants. https://www.accaglobal.com/policy-and-insights/reports/2021/ethics-ai-adoption.html
ACCA. (2023). Building the foundations for trusted artificial intelligence. Association of Chartered Certified Accountants. https://www.accaglobal.com/policy-and-insights/reports/2023/building-foundations-trusted-ai.html
AICPA & CIMA. (n.d.). Making good decisions: building trust in a digital world. Association of International Certified Professional Accountants. https://www.aicpa-cima.com/resources/landing/ethics-technology
Ballantine, J. A., Boyce, G., & Stoner, G. (2024). A critical review of AI in accounting education: Threat and opportunity. Critical Perspectives on Accounting, 99, 102711. https://doi.org/10.1016/j.cpa.2024.102711
CPA Australia. (2024). AI Ethics for Modern Professionals. CPA Australia Professional Development. https://www.cpaaustralia.com.au/professional-development/courses-and-events/ai-ethics-for-modern-professionals
Dell, S., Akpan, M., & Carr, A. (2024). Aligning artificial intelligence with ethical accountancy: A global perspective on emerging frameworks. Corporate Ownership & Control, 21(1), 47-54. https://doi.org/10.22495/cocv21i1art5
Deloitte. (2025). Deloitte expands its global suite of GenAI and agentic AI capabilities in Omnia, advancing the audit experience (Press release). Deloitte.
IESBA. (2024). IESBA Snapshot: Ethics and Independence Approach to the Use of Technology. International Ethics Standards Board for Accountants. https://www.ethicsboard.org/news-events/2026-06/iesba-snapshot-ethics-and-independence-approach-use-technology
KPMG. (2024). KPMG AI-driven audit with MindBridge. MindBridge Analytics. https://www.mindbridge.ai/docs/resources/customer-stories/KPMG/KPMG-AI-Driven-Audit-with-MindBridge_02262024.pdf
Marr, B. (2018). Artificial intelligence in practice: How 50 successful companies used AI and machine learning to solve problems. Wiley.
Mökander, J. (2023). Managing algorithmic risks: AI governance and professional responsibility. AI & Society, 38(4), 1123-1135. https://doi.org/10.1007/s00146-022-01454-7
Omoteso, K. (2012). The application of artificial intelligence in auditing: Looking back to the future. Expert Systems with Applications, 39(9), 8490-8495. https://doi.org/10.1016/j.eswa.2012.01.098
PwC. (2020). GL.ai: PwC’s next-generation audit technology. PwC Middle East. https://www.pwc.com/m1/en/events/socpa-2020/documents/gl-ai-brochure.pdf
Richins, G., Stapleton, A., Stratopoulos, T., & Wong, C. (2017). Big data analytics: Opportunity or threat for the accounting profession? Journal of Information Systems, 31(3), 63-79. https://doi.org/10.2308/isys-51805
Schweitzer, B. (2024). Artificial Intelligence (AI) Ethics in Accounting. Journal of Accounting, Ethics & Public Policy (JAEPP), 25(1), 67. https://doi.org/10.60154/jaepp.2024.v25n1p67
Tan, B. S., & Low, K. Y. (2019). Competing logics: Data analytics and AI in accounting practice. Accounting Horizons, 33(3), 89-110. https://doi.org/10.2308/acch-52452
Thuật toán và trách nhiệm giải trình:
Rủi ro hệ thống, tính bền vững theo tiêu chí ESG
và sự phát triển của khuôn khổ đạo đức nghề kế toánTóm tắt:
Bài báo này phân tích một cách có hệ thống những tác động hai mặt của trí tuệ nhân tạo (AI) trong lĩnh vực kế toán, làm rõ các lợi ích tiềm năng. Nghiên cứu lập luận rằng việc ứng dụng AI ngày càng sâu rộng trong các hoạt động kế toán và tài chính đòi hỏi phải đánh giá lại một cách toàn diện và hiện đại hóa các khuôn khổ đạo đức và chuẩn mực nghề nghiệp hiện hành. Trên cơ sở tham chiếu các chuẩn mực đạo đức và hướng dẫn nghề nghiệp hiện hành do những tổ chức quốc tế hàng đầu ban hành, bài báo nhấn mạnh vai trò không thể thay thế của xét đoán chuyên môn, thái độ hoài nghi nghề nghiệp và trách nhiệm giải trình về đạo đức trong quá trình ra quyết định có sự hỗ trợ của AI. Trên cơ sở đó, nghiên cứu khẳng định rằng những tiến bộ công nghệ cần đi đôi với cơ chế giám sát đạo đức chặt chẽ nhằm bảo đảm tính chính trực nghề nghiệp, tăng cường trách nhiệm giải trình và duy trì niềm tin của công chúng đối với nghề kế toán (Ballantine, 2024; IESBA, 2024).
Từ khóa: trí tuệ nhân tạo, đạo đức nghề nghiệp kế toán, tính minh bạch, trách nhiệm nghề nghiệp, ESG, IESBA, ACCA, AICPA
[Tạp chí Công Thương - Các kết quả nghiên cứu khoa học và ứng dụng công nghệ số 28 tháng 10 năm 2026]